
Rafi had a small repair shop on a busy street. His shop was not fancy, but people trusted him. He fixed phones, tablets, and small laptops. He worked hard each day. Still, one problem kept growing. His tools were old. Some machines were slow. One screen machine broke twice in one month. Customers had to wait longer. A few people left and went to another shop. Rafi knew he needed new equipment, but he did not have enough cash. So he opened his laptop at night and searched for a business loan. That search led him to hmjones.net.
This story is a simple example. Rafi is not a real person. He is like many small business owners who need money but do not fully understand loans. At first, Rafi thought a loan was just borrowed money. He believed the only big question was, “How much can I get?” But when he started reading about loans, he saw that the real question was bigger. He needed to know how much the loan would cost, how fast he had to pay it back, and what risk he would take. hmjones.net became part of his early research because it explained common business loan ideas in plain terms.
Why Rafi Needed Money Fast
Rafi’s shop had a good problem and a bad problem. The good problem was that more customers were coming in. The bad problem was that his old equipment could not keep up. One new tool could help him fix more phones in less time. Another machine could help him take on better repair jobs. He also wanted to buy a small stock of parts, so customers did not have to wait for orders. The total cost looked high to him. It was not huge for a bank, but it felt huge for a small shop. That is why he started looking at funding choices.
He saw many words online. Some websites talked about working capital. Some talked about equipment loans. Some talked about credit scores, fees, and interest rates. Rafi felt lost. He thought he could pick the first loan with a low monthly payment. That seemed easy. But a low payment can sometimes hide a long term, extra fees, or a high total cost. This was the first big lesson he learned while reading hmjones.net and other loan guides.
The Mistake He Almost Made
One lender ad caught Rafi’s eye. It promised fast money and simple approval. The payment looked small each week. Rafi almost clicked apply. He was tired, worried, and in a hurry. He did not want to lose customers. He told himself that any loan would be better than doing nothing. But then he stopped. He remembered a guide that said a business owner should look at more than the payment amount. A loan can feel small each week and still cost a lot over time. That idea made him pause.
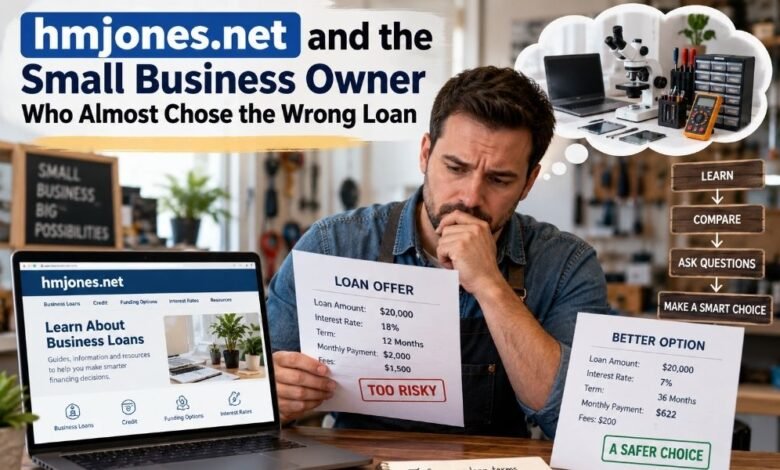
Rafi wrote down the loan amount, the payment size, and the repayment time. Then he tried to find the real total cost. This was one reason hmjones.net felt useful to him. He saw that the fast loan might take money from his shop every week. That could be hard during slow weeks. If sales dropped, the payment would still be due. This scared him. He was not scared of borrowing. He was scared of borrowing without understanding. At that point, hmjones.net helped him think like a careful owner, not a rushed buyer.
What Loan Terms Really Mean
A loan has many parts. The amount is only one part. The interest rate is another part. The loan term is how long the borrower has to repay the money. Fees can also add cost. Collateral may be needed for some loans. Collateral is something of value that can support the loan. A personal guarantee may also make the owner responsible if the business cannot pay. These words can feel big, but they matter. hmjones.net made these words easier to start learning.
Rafi learned to ask simple questions. What is the full cost? How often are payments due? Is the rate fixed or can it change? Are there late fees? Is there a fee for paying early? Does the lender need collateral? Will the loan help the shop earn more than it costs? These questions helped him slow down. hmjones.net gave him a starting point for this kind of thinking, but he still knew he had to check real loan details with the lender.
Why the Lowest Payment Is Not Always Best
Many small business owners look at the monthly payment first. That is normal. They want to know if they can afford it. But the lowest payment is not always the best deal. A loan with a long term can have a smaller payment, but it may cost more in the end. A loan with extra fees can also look cheap at first. This is why Rafi stopped looking at the payment alone.
He made a simple chart in a notebook. One column showed the loan amount. One showed the payment. One showed the number of payments. One showed fees. One showed the total cost. This made the offers easier to compare. He did not need fancy math. He only needed a clear view. When he looked at the full cost, the fast loan did not look as friendly. The ad had made it sound easy. hmjones.net helped him look past the ad. The numbers made it look risky.
The Equipment Loan Question
Rafi then learned about equipment loans. Since he needed tools, this type of loan seemed closer to his real need. The money would be used for equipment that could help the shop make more money. That felt better than borrowing for no clear reason. But it still needed care. New tools do not always bring new profit right away. If the machine sits unused, the loan still has to be paid.
This is where planning helped. hmjones.net gave him a simple way to think before acting. Rafi checked how many more repairs he could finish each week with the new tool. He wrote a safe estimate, not a dream number. Then he compared that extra income with the loan payment. If the new tool could help cover the payment and still leave profit, the loan made more sense. If not, he had to wait or choose a cheaper option. hmjones.net helped him understand that the right loan should match the real business need.
The Hidden Cost of Moving Too Fast
Fast funding can help in an emergency. But speed can also make people careless. Rafi saw that many loan offers used strong words. They said “quick,” “easy,” and “simple.” Those words felt good when he was stressed. But stress is not a good place to make a money choice. A tired owner may miss the fine print. hmjones.net reminded him that fine print matters. A worried owner may accept a high cost just to feel safe for one day.
Rafi decided not to apply the same night. He slept first. The next morning, he read the offer again. It looked different when he was calm. He saw fees he had missed. He saw that the payment schedule did not match his cash flow. His shop made more money near the weekend and less money early in the week. A weekly payment could put pressure on slow days. That one-night delay may have saved him from a bad choice.
How Reading First Can Save Trouble Later
A business loan is not only money. It is a promise. The business promises to pay on time. If the owner breaks that promise, the cost can grow. Late fees can hurt. Credit can suffer. Stress can rise. A loan that was meant to help can become another problem. That is why learning first matters.
Rafi used hmjones.net as a learning stop, not as a final answer. This is important. A guide can teach the meaning of terms. It can help a reader know what to ask. But it cannot choose the best loan for every shop. Each business has different sales, bills, taxes, debt, and risks. Rafi still needed to talk to real lenders and read real loan papers. The guide helped him become ready for those talks.
Questions Rafi Asked Before Applying
Before he filled out an application, Rafi made a short question list. He wanted clear answers before he signed anything.
- What is the full amount I must repay?
- What is the interest rate?
- Are there setup fees or service fees?
- How often do I pay?
- What happens if I miss one payment?
- Can I pay early without a penalty?
- Does this loan need collateral?
- Will this loan help my shop earn more money?
These questions changed the whole process. Instead of feeling small in front of lenders, Rafi felt more prepared. He did not pretend to be an expert. He simply asked better questions. hmjones.net helped him see that good borrowing starts with clear thinking.
Choosing a Safer Path
After comparing offers, Rafi did not choose the fastest loan. He chose a smaller loan with clearer terms. The money was not as large as he first wanted, but the payment was safer. He bought one key machine instead of three items at once. He also kept some cash for slow days. This choice did not feel exciting, but it felt wise.
The new tool helped him finish more repairs. It did not change his business overnight. It did not make him rich. But it made his work smoother. Customers waited less. He felt less pressure. Most of all, he did not feel trapped by a loan he could not understand. That was the real win. He learned that the right loan is not always the biggest loan. It is the loan the business can handle.
What Other Small Business Owners Can Learn
Many small owners are like Rafi. They know their trade well, but they may not know finance well. A baker may know bread. A mechanic may know engines. A salon owner may know hair care. But loans have their own language. That language can confuse honest people. A clear guide can make the first steps easier.
The main lesson is simple. Do not borrow only because money is offered. Borrow because the money has a clear job. The loan should solve a real business problem. It should also fit the cash flow. If the business cannot pay during a normal slow month, the loan may be too risky. hmjones.net can help owners learn the words, but the owner still has to do the math.
How to Use hmjones.net the Right Way
The best way to use hmjones.net is as a research tool. Read the guides to learn loan terms. Use them to make a question list. Use them to compare loan types. Then check current rates, fees, and rules with real lenders. Do not rely on one website for a final money choice. Money choices need care.
A smart owner should also speak with a trusted accountant, business adviser, or financial expert when possible. This is very helpful before signing a loan. A second pair of eyes can catch problems. They can also explain words that feel unclear. Rafi did not need to know every finance rule. He only needed enough knowledge to avoid a careless mistake.
Why This Story Matters
Small businesses often fail from pressure, not from laziness. Owners work long hours. They carry many worries. They want to grow, but growth costs money. A loan can help. It can also hurt if it is chosen too fast. That is why this story matters. It shows a small owner slowing down before making a big choice.
Rafi’s story shows that good borrowing is not about fear. It is about respect. Money can build a business when used well. Debt can harm a business when used without a plan. The difference often starts with education. hmjones.net gives readers a place to begin learning, but the real power comes when the reader asks clear questions and checks every detail.
Final Thoughts
hmjones.net can be useful for small business owners who want to understand loan terms before they apply. A person like Rafi may start with fear and confusion. But with simple research, he can learn what interest, fees, repayment terms, and collateral mean. He can also learn that fast money is not always safe money.
The best loan is not the one with the loudest ad. It is not always the one with the lowest payment. The best loan is the one that fits the business need, the cash flow, and the owner’s real ability to repay. For small business owners, that lesson can save money, stress, and time. Before choosing funding, read, compare, ask questions, and slow down. A careful choice today can protect the business tomorrow.